Home » Calculate the Financial Return of a Lean Improvement
Calculate the Financial Return of a Lean Improvement
Contents
Evaluate a Lean project by separating measurable operating change from financial value the business can actually realize. Released labor time is capacity; it becomes a cash saving only when spending falls, overtime is avoided, output that can be sold is produced, or another verified financial benefit occurs. This worked example uses fictional data and is not a real company case.
Choose one process and measurement window. Record the baseline condition, job mix, accepted output, time definition, scrap/rework, inventory, labor hours, and any existing overtime or outside services. Agree with finance and the process owner how a benefit will be recognized. Use the same scope before and after the improvement.
Separate four categories in the business case:
Cash savings: documented reduction in spending, such as avoided overtime or purchased service.
Incremental contribution: additional accepted units that can be sold, multiplied by the approved contribution margin per unit.
Released capacity: time made available for other work; report separately unless it is converted to a recognized financial benefit.
Cost avoidance or risk reduction: describe the basis and uncertainty; do not book it as a realized saving without finance approval.
Worked setup-time example with stated assumptions
Fictional assumptions: a fixture change reduces setup by 30 minutes per setup; the cell performs 2 qualifying setups per shift, 250 shifts per year; the loaded labor rate is $35 per hour; startup cost is $4,500 for the fixture and $1,000 for training; ongoing annual maintenance is $500. The released capacity is 0.5 hour × 2 setups/shift × 250 shifts/year = 250 hours/year. Its labor-equivalent value is 250 × $35 = $8,750 per year, but it is not automatically cash savings.
Assume a finance-approved pilot converts part of that capacity into 100 hours of avoided overtime at a $52/hour cash cost, and documented material scrap falls by 20 units at $80 variable material cost per unit. These additional hypothetical conditions produce $5,200 + $1,600 = $6,800 gross annual cash benefit. After $500 annual maintenance, recurring net benefit is $6,300.
Illustrative annual benefit bridge; all values are fictional USD
Item
Calculation
Amount
Financial treatment
Released capacity
0.5 h/setup × 2 setups/shift × 250 shifts × $35/h
$8,750
Capacity value only; not counted as cash benefit
Avoided overtime
100 h/year × $52/h
$5,200
Cash benefit only if overtime would otherwise be paid and is actually avoided
Scrap material reduction
20 units/year × $80/unit
$1,600
Cash benefit only if material use and scrap records support it
Gross recurring benefit
$5,200 + $1,600
$6,800
Before ongoing cost
Annual maintenance
Assumed annual cost
−$500
Ongoing cost
Net recurring benefit
$6,800 − $500
$6,300
Subject to finance verification
Startup cost
$4,500 fixture + $1,000 training
$5,500
One-time investment
Simple payback
$5,500 ÷ $6,300/year × 12
10.5 months
Assumes steady annual benefits and excludes discounting and ramp-up
First-year simple ROI
($6,300 − $5,500) ÷ $5,500 × 100
14.5%
Net first-year benefit divided by startup cost
Do not add the $8,750 capacity value to the $6,800 cash benefit: the same released hours may be what enables the overtime reduction, so counting both would double-count value. Replace the assumptions with evidence, confirm the cost basis and time period, and state whether taxes, financing, inflation, ramp-up, and working capital are included.
Test the sensitivity before approval
Illustrative sensitivity to realized annual gross benefit; ongoing cost stays at $500/year
Scenario
Gross annual benefit
Net annual benefit after maintenance
Simple payback on $5,500 startup
Low: 50% of base gross benefit
$3,400
$2,900
$5,500 ÷ $2,900 × 12 = 22.8 months
Base assumptions
$6,800
$6,300
10.5 months
High: 125% of base gross benefit
$8,500
$8,000
$5,500 ÷ $8,000 × 12 = 8.3 months
This sensitivity is an illustration, not a forecast. If the low case does not meet the company’s investment rule, collect better evidence or redesign the trial before purchasing equipment.
Use a benefit verification sheet
Baseline and post-change period, process boundary, product mix, and accepted quantity.
Setup start/stop definition, number of observations, and shift coverage.
Startup, training, maintenance, and other recurring costs with source records.
Cash benefit owner, finance-approved calculation, actual realization date, and evidence.
Capacity released, reported separately from cost savings or contribution margin.
Quality, safety, delivery, staffing, and inventory guardrails.
A Lean project can shorten a queue or free operator time without reducing the company’s cash expense. Before calling a result “savings,” identify the cost that will actually change in the ledger and the person who verifies it. Keep four benefit types separate: cash costs that are removed, costs avoided against a documented alternative, released capacity that can be used for other work, and working capital tied up in inventory. They have different evidence and should not be added together as if they were the same cash flow.
For a fictional setup improvement, assume a $6,000 tooling investment and $300 per month of verified recurring cash savings. Simple payback is $6,000 ÷ $300 per month = 20 months. The monthly savings must come from a defined cost that really changes, such as a canceled outside service or actual overtime no longer paid. If operators use the released time to produce other needed work, that can be valuable capacity, but it is not cash savings unless the financial plan shows a corresponding expense reduction or avoided expenditure.
Do not book the value of faster production as revenue unless the business can sell the additional output and finance confirms the contribution margin and timing. A shipment may preserve a customer relationship, but retained sales are not automatically incremental profit. A lower WIP balance may release working capital, but multiplying the reduction by unit cost does not make that amount recurring annual savings. Report the operational change and financial classification separately.
Establish the baseline before the test
Choose a stable product family, process boundary, and comparison period. Record good units shipped, scrap quantity and disposition, changeover minutes, overtime hours actually paid, labor assignment, WIP quantity and age, equipment downtime, and any outside processing or expediting charge relevant to the proposed change. Write down the source for each number and whether it is measured, estimated, or finance-approved. A baseline that mixes different product mix, demand, shifts, and accounting periods cannot support a clean comparison without normalization.
For scrap, distinguish quantity from cost. Record material mass or pieces, the cost basis approved by finance, whether the material is recoverable, and whether the recorded value includes labor or overhead. For changeover, record start/end definitions and the number of changes; fewer minutes can improve available capacity without changing payroll. For overtime, compare paid hours and premium dollars in payroll or approved finance reports, not a supervisor’s estimate of hours “saved.” For inventory, count accepted, held, and obsolete stock separately and use the company’s working-capital method.
Lean improvement benefit classification worksheet; fictional project should be replaced with local evidence
Benefit claim
Required baseline and after evidence
Financial treatment
Verifier
Scrap reduction
Scrap quantity by material and reason; approved unit cost; actual disposition.
Cash only for variable cost avoided and not recovered elsewhere.
Quality and finance
Less overtime
Paid hours, premium rate, comparable volume, and schedule.
Cash when payroll expense is actually reduced.
Operations and finance
Freed labor capacity
Hours released and documented redeployment to needed work.
Capacity benefit; exclude from cash savings unless expense changes.
Operations owner
Lower WIP
Accepted units and value under consistent accounting rules.
Working-capital or carrying-cost effect; not automatically recurring savings.
Materials and finance
Avoided outside service
Approved quote or planned purchase and proof the spend was canceled.
Avoided cost against a documented alternative.
Purchasing and finance
Improved delivery
Orders due and on time, same customer and product scope.
Operational result; revenue or margin only when separately validated.
Customer service and finance
Use a simple model with timing and assumptions
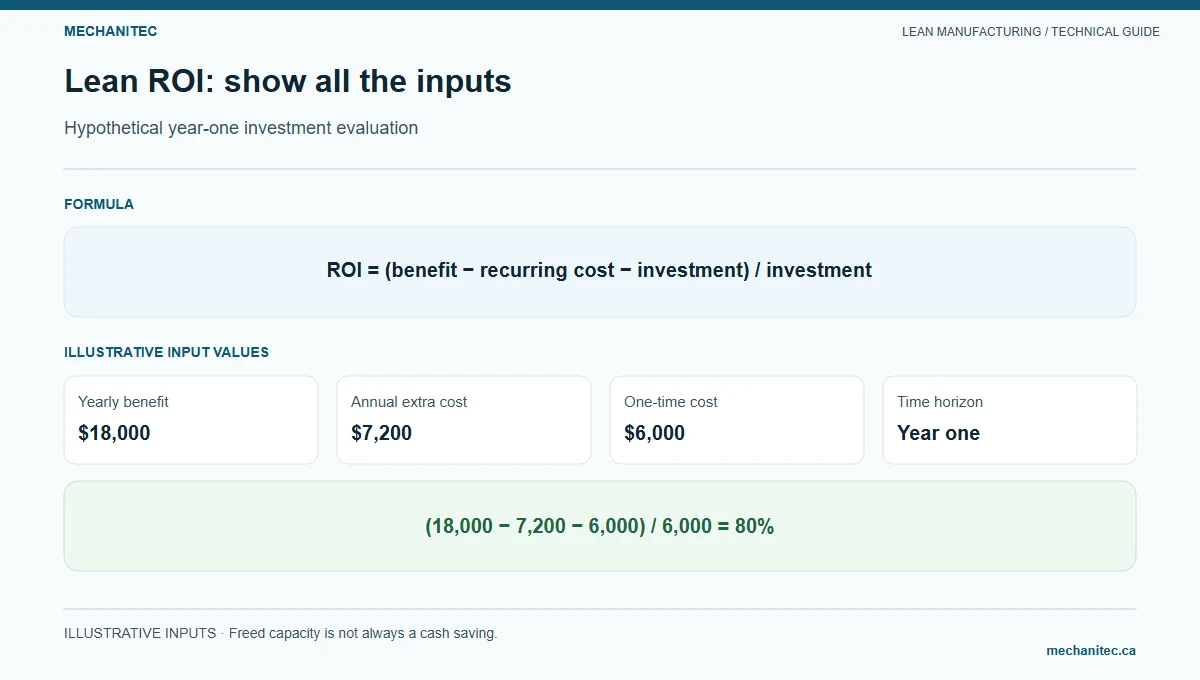
For a single investment with stable monthly net cash savings, simple payback in months = initial investment ÷ verified monthly net cash benefit. Net benefit should subtract recurring operating cost introduced by the improvement. For a multi-period project, include when cash is spent and when savings begin. A simple ROI over a stated horizon is (verified benefits during the horizon − investment and added operating cost) ÷ investment × 100. State the horizon and do not call payback “ROI”; they answer different questions.
In the example, assume the $300 monthly cash benefit starts after a one-month installation and validation period, and there is no added monthly maintenance cost. The simple 20-month payback begins when the recurring benefit begins, so cash recovery from project approval occurs around month 21. If the tool requires $50 monthly maintenance, net benefit is $250 and simple payback after start-up becomes $6,000 ÷ $250 = 24 months. The model should show this cost rather than hiding it in a general project budget.
Sensitivity of the fictional $6,000 tooling investment
Verified monthly net cash benefit
Simple payback after savings start
Decision interpretation
$150
$6,000 ÷ $150 = 40 months
Test whether the project remains justified at low benefit.
$300
$6,000 ÷ $300 = 20 months
Base case only if finance verifies the monthly expense change.
$450
$6,000 ÷ $450 = 13.3 months
High case; document the operational and financial evidence needed.
Label every assumption: investment quote, installation timing, savings start date, monthly benefit, useful life, maintenance, volume, scrap recovery, discount rate if used, and approval threshold. Show low, base, and high cases for inputs that can move the decision. A sensitivity table does not turn a guess into evidence; it shows which assumption needs verification before approval.
Verify benefits after implementation
Assign a benefit owner and an independent verifier before the project begins. The owner maintains the operational measure; finance validates cost treatment and cash realization. Record the baseline period, implementation date, stabilization period, comparison window, product and shift scope, source system, and any exclusions. Check whether demand, product mix, staffing, wage rates, supplier prices, or accounting policy changed at the same time.
At the first monthly review, compare actual cash expense with the baseline or approved alternative. At later reviews, confirm that the change persists and that operating costs did not move to another department. If savings depend on canceling overtime, verify payroll. If they depend on scrap, verify the disposition and actual variable cost. If a benefit is only capacity or avoided risk, report it in that category without adding it to booked cash.
Close the benefit sheet with the formula, source, reviewer, date, and accepted classification. If the result is lower than projected, report the gap and revise the model rather than changing the baseline after the fact. If benefits are not measurable, mark them as unverified and set a next measurement date. This gives a plant manager a credible decision record even when the project has operational value beyond its direct financial return.
Do not treat sales, inventory, or capacity as immediate savings
More output can become revenue only when demand exists, product can ship, and the incremental sale produces margin after variable costs. Revenue is not profit. A late order avoided may protect service, but the value depends on a documented alternative and customer context; it should not be claimed as cash without evidence. Inventory reduction can release cash once actual purchases or work-in-process are reduced, but a one-time release is different from recurring annual savings. Faster setup may create capacity, yet payroll remains unchanged if the same people work the same paid hours.
These categories can still matter. Show capacity in hours per month, WIP in units and approved value, delivery in orders on time, and risk reduction in the specific exposure controlled. Use a separate financial translation only when the responsible finance owner approves it. This prevents a promising project from losing credibility through an overstated business case.
Prepare a decision summary that a reviewer can reproduce
Put the decision, investment, verified benefit categories, payback basis, risk, and next review date on one page. Attach the calculation sheet and source records rather than copying a single savings number into a presentation. State the decision requested: approve a bounded pilot, release capital, defer pending evidence, or stop. If the project is approved as a pilot, name the limits on spend and the person who can authorize a scope change.
At the end of the stated horizon, compare actual cash flows with the forecast and record the variance. Keep the original assumptions so the team can explain whether the difference came from implementation timing, benefit size, volume, added operating cost, or accounting treatment. A reproducible model supports the next decision even when the project does not meet its initial estimate.
Record the approval and accountable owner.
Document cash-flow timing and approval
For capital review, show when the investment is committed, when installation occurs, when the process stabilizes, and when the recurring benefit can first appear. Separate one-time implementation cost from monthly operating cost and show both before and after tax or financing only when the company’s approved model requires it. A simple payback is not a discounted cash-flow analysis. Use the finance team’s required method for capital approval and retain the $300 monthly example only as a transparent arithmetic case. Record who verifies each benefit, the period reviewed, and the date the model will be reconciled to actual results.